VAT invoice checklist (UK)
What HMRC says a VAT invoice must show, from VAT Notice 700/21, section 4. A full VAT invoice is the usual kind; a simplified one is allowed for smaller supplies.
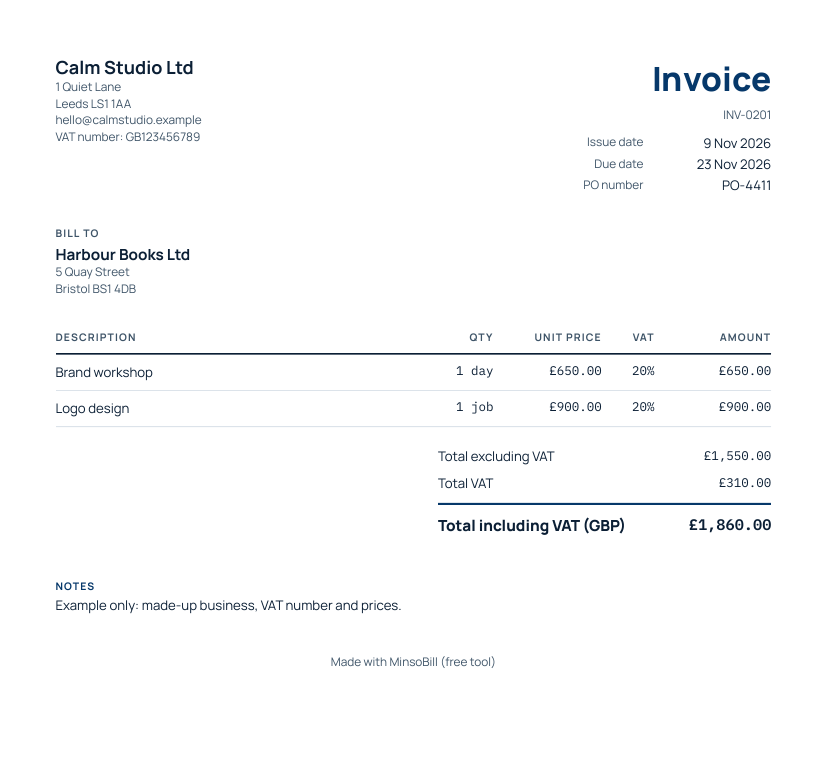
A full VAT invoice must show
- A sequential number, based on one or more series, that uniquely identifies the invoice
- The time of supply (tax point)
- The date of issue, where it is different from the time of supply
- Your name, address and VAT registration number
- The name and address of the customer
- A description sufficient to identify the goods or services
- For each description: the quantity of goods or extent of services, the VAT rate and the amount payable excluding VAT
- The gross total amount payable, excluding VAT
- The rate of any cash discount offered
- The total amount of VAT chargeable, in sterling
- The unit price
A simplified VAT invoice
If you are not a retailer and the supply is £250 or less (including VAT), you may issue a simplified invoice instead. It shows:
- your name, address and VAT registration number
- the time of supply (tax point)
- a description that identifies the goods or services
- for each VAT rate, the total amount payable including VAT, and the VAT rate charged
Exempt supplies must not be included on a simplified invoice. For more than £250, issue a full or a modified VAT invoice.
Special cases
Special rules apply to invoices issued under a margin scheme or subject to a reverse charge. Follow the rules for those supplies.
If you are not VAT registered
Your invoice must still include:
- a unique identification number
- your company name, address and contact information
- the company name and address of the customer you are invoicing
- a clear description of what you are charging for
- the date the goods or service were provided (supply date)
- the date of the invoice
- the amount or amounts being charged, and the total amount owed
Sole traders and limited companies have a few more details to add; GOV.UK lists them.
Sources
Last checked 9 November 2026.
- HMRC: VAT Notice 700/21, section 4.1, details to include on a VAT invoice
- HMRC: VAT Notice 700/21, section 4.5, simplified invoices
- GOV.UK: invoices, what they must include
This is general information, not legal or tax advice.
Save and send with MinsoBill
Keep your invoices and quotes in one place, send them by email or link, and see when the link was opened. Free during early access.
Save and send with MinsoBill