VAT invoice checklist (EU)
The EU VAT Directive (Council Directive 2006/112/EC, Article 226) sets the details a VAT invoice must show in every EU country. Each country can add national rules in some areas.
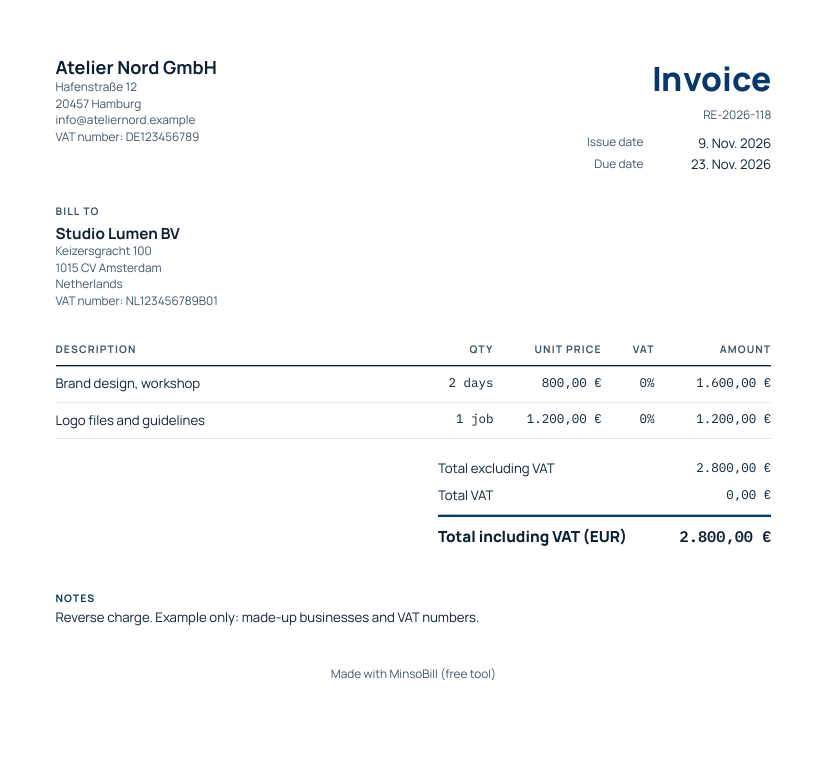
A full VAT invoice must show
- The date of issue
- A unique sequential number identifying the invoice
- Your VAT identification number
- Your full name and address, and your customer's
- Your customer's VAT identification number, if the customer is liable for the tax on the transaction
- A description and the quantity of the goods or services
- The unit price, excluding tax and any discounts or rebates not included in it
- The date of the transaction or payment, if it is different from the invoice date
- The VAT rate applied and the VAT amount payable, broken down by rate or exemption
A simplified VAT invoice
Where a simplified invoice can be used, it must show:
- the date of issue
- your VAT identification number
- the type of goods or services supplied
- the VAT amount payable, or the information needed to calculate it
- on a credit note or other document amending an invoice: a specific, unambiguous reference to the original invoice and the details being changed
Reverse charge and other extra details
If your customer is liable for the tax (the reverse-charge procedure), the invoice must say ‘reverse charge’. For example, when you supply a service to a business in another EU country, the VAT does not appear on your invoice: your customer accounts for it in their own country.
- Exempt transactions: a reference to the law exempting it, or another reference showing it is exempt.
- Self-billing (the customer issues the invoice): the words ‘self-billing’.
- A margin scheme: a reference to the scheme, such as ‘margin scheme — travel agents’.
- Cash accounting: the words ‘cash accounting’.
- A tax representative liable for the tax: their VAT identification number, full name and address.
Once an invoice includes the required information, no EU country may refuse it as proof for deducting VAT by asking for more. You can always add other information. European Commission: VAT invoicing rules
Sources
Last checked November 9, 2026.
- EUR-Lex: Council Directive 2006/112/EC (the VAT Directive), Article 226
- European Commission: VAT invoicing rules
- Your Europe: VAT on invoices
This is general information, not legal or tax advice.
Save and send with MinsoBill
Keep your invoices and quotes in one place, send them by email or link, and see when the link was opened. Free during early access.
Save and send with MinsoBill